Every January, somebody asks Julie Underwood, CPA, whether their golden retriever counts as a business expense because he "guards the office" by sleeping under her desk. The honest answer is almost always no. But buried in the tax code are a handful of narrow, well-documented situations where a dog really can reduce what you owe the IRS. If you're a farmer, a service-business owner, or someone managing a chronic condition, it's worth knowing exactly where that line sits, so you claim what you're entitled to and skip the deduction that gets flagged in an audit.
This matters more in Brookings, SD than in most places. Farmers and agribusiness operators here often keep working dogs for livestock protection, and service-based business owners sometimes keep a dog on the premises for legitimate security reasons. The IRS doesn't care what breed you have or how much you love the animal. It cares about how the dog functions in your business or your medical care, and whether you can prove it.
Why pets don't qualify as a deduction
IRS Publication 535 (opens in new tab) sets the baseline rule for business expenses: a cost has to be ordinary and necessary for carrying on your trade or business. A family pet, even one that lives at a business address, fails that test because the primary reason it exists is personal companionship, not commerce. Vet bills, food, grooming, and boarding for a household dog are personal expenses in the same category as your own groceries. That's true whether the dog is a labradoodle in Brookings or a bulldog in Sioux Falls.
The confusion usually starts because a dog does something useful. It barks at the mail carrier, it keeps the shop cat population down, it makes clients smile in the lobby. Usefulness isn't the standard. The standard is whether the dog's role is documented, ongoing, and integral to how the business actually operates. Occasional or incidental usefulness doesn't convert a family pet into a business dog write-off.
Service and guide dogs get real tax relief
This is the deduction most people miss because they're looking in the wrong publication. IRS Publication 502 (opens in new tab) allows the cost of buying, training, and maintaining a guide dog or other service animal as a medical expense if the dog assists someone with a visual, hearing, or other physical disability. That includes food, grooming, and veterinary care required to keep the animal healthy enough to perform its duties.
The catch is the same one that applies to every medical deduction: it only helps if your total qualifying medical expenses, combined with everything else in that category, clear 7.5% of your adjusted gross income, and you itemize instead of taking the standard deduction—a reason tax-advantaged planning matters when medical costs are part of your overall financial picture. For a lot of individual taxpayers that threshold is hard to reach with a service dog alone. But if you're already itemizing due to other medical costs, the dog-related expenses are legitimately part of that math. This is a service animal tax deduction claim, not a therapy dog deduction under IRS rules, and the distinction matters—one many high-net-worth individuals miss by waiting until year-end to plan.
Therapy dogs and the fine print the IRS cares about
Here's where people run into trouble. A therapy dog that visits nursing homes or schools for emotional comfort is not automatically deductible, even when the visits are genuinely valuable. The IRS treats emotional support animals differently from trained service animals performing a specific task tied to a diagnosed disability. Publication 502 is built around functional assistance, not general comfort. A therapy dog deduction under IRS rules generally requires the dog to be specifically trained to perform tasks related to a medical condition, and that training and its purpose need to be documented, usually by a treating physician.
If your dog's role is emotional support without task-specific training tied to a diagnosis, don't count on the medical expense deduction. That doesn't mean the dog isn't worth every penny to your wellbeing. It means the tax code hasn't caught up to that particular kind of value.
Guard dogs can be a legitimate business expense
A guard dog business expense is one of the more defensible dog-related deductions, and it's the one we see most often among Brookings and Kingsbury County business owners who store equipment, inventory, or livestock feed on-site. To hold up, the arrangement needs to look like a real security decision, not a rationalization for keeping a pet at the shop.
That means the dog is a breed suited to guarding, it's kept primarily at the business location rather than the owner's home, and there's a documented business reason, like a history of theft, high-value equipment, or an insurance requirement. Under Publication 535's ordinary-and-necessary standard, food, veterinary care, and training costs for that dog can be deducted as a business dog tax write-off. Keep receipts, keep the dog on-site consistently, and keep a simple log or photo record showing the dog living and working at the business, not at your kitchen table on weekends.
Working dogs on the farm get different treatment
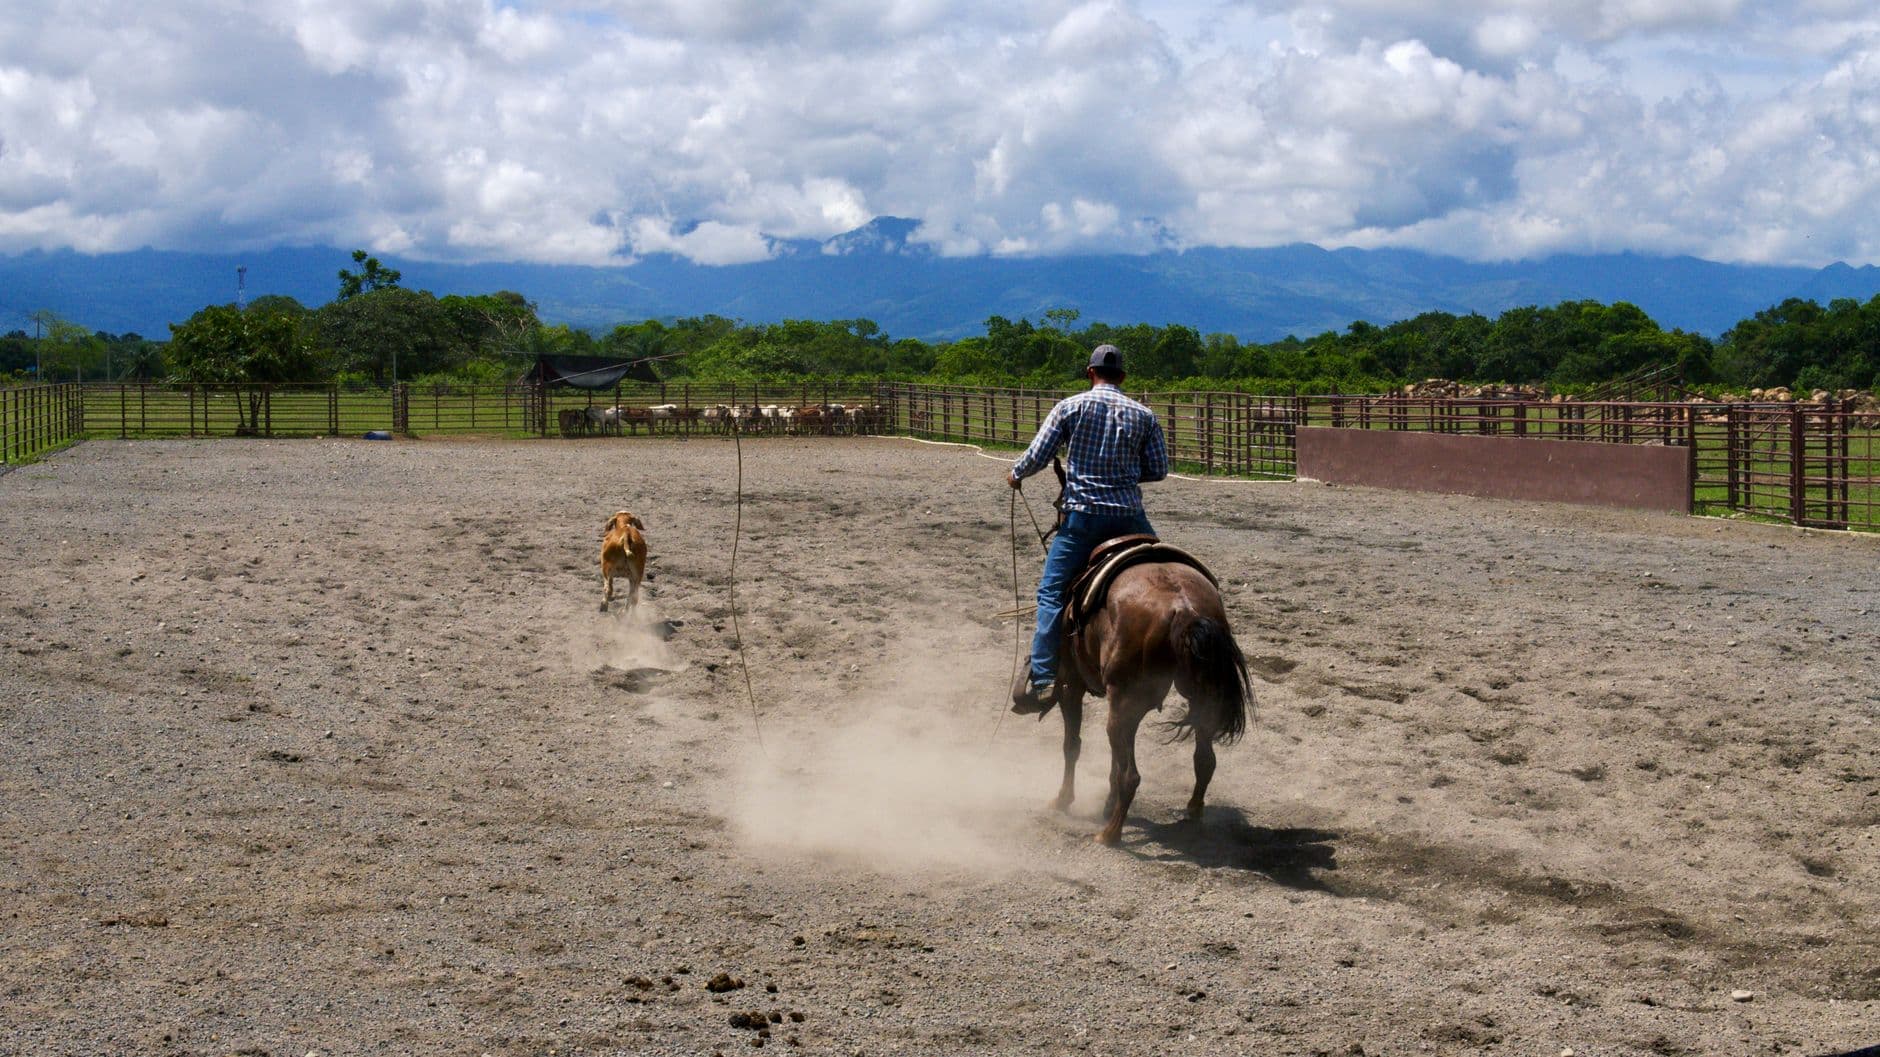
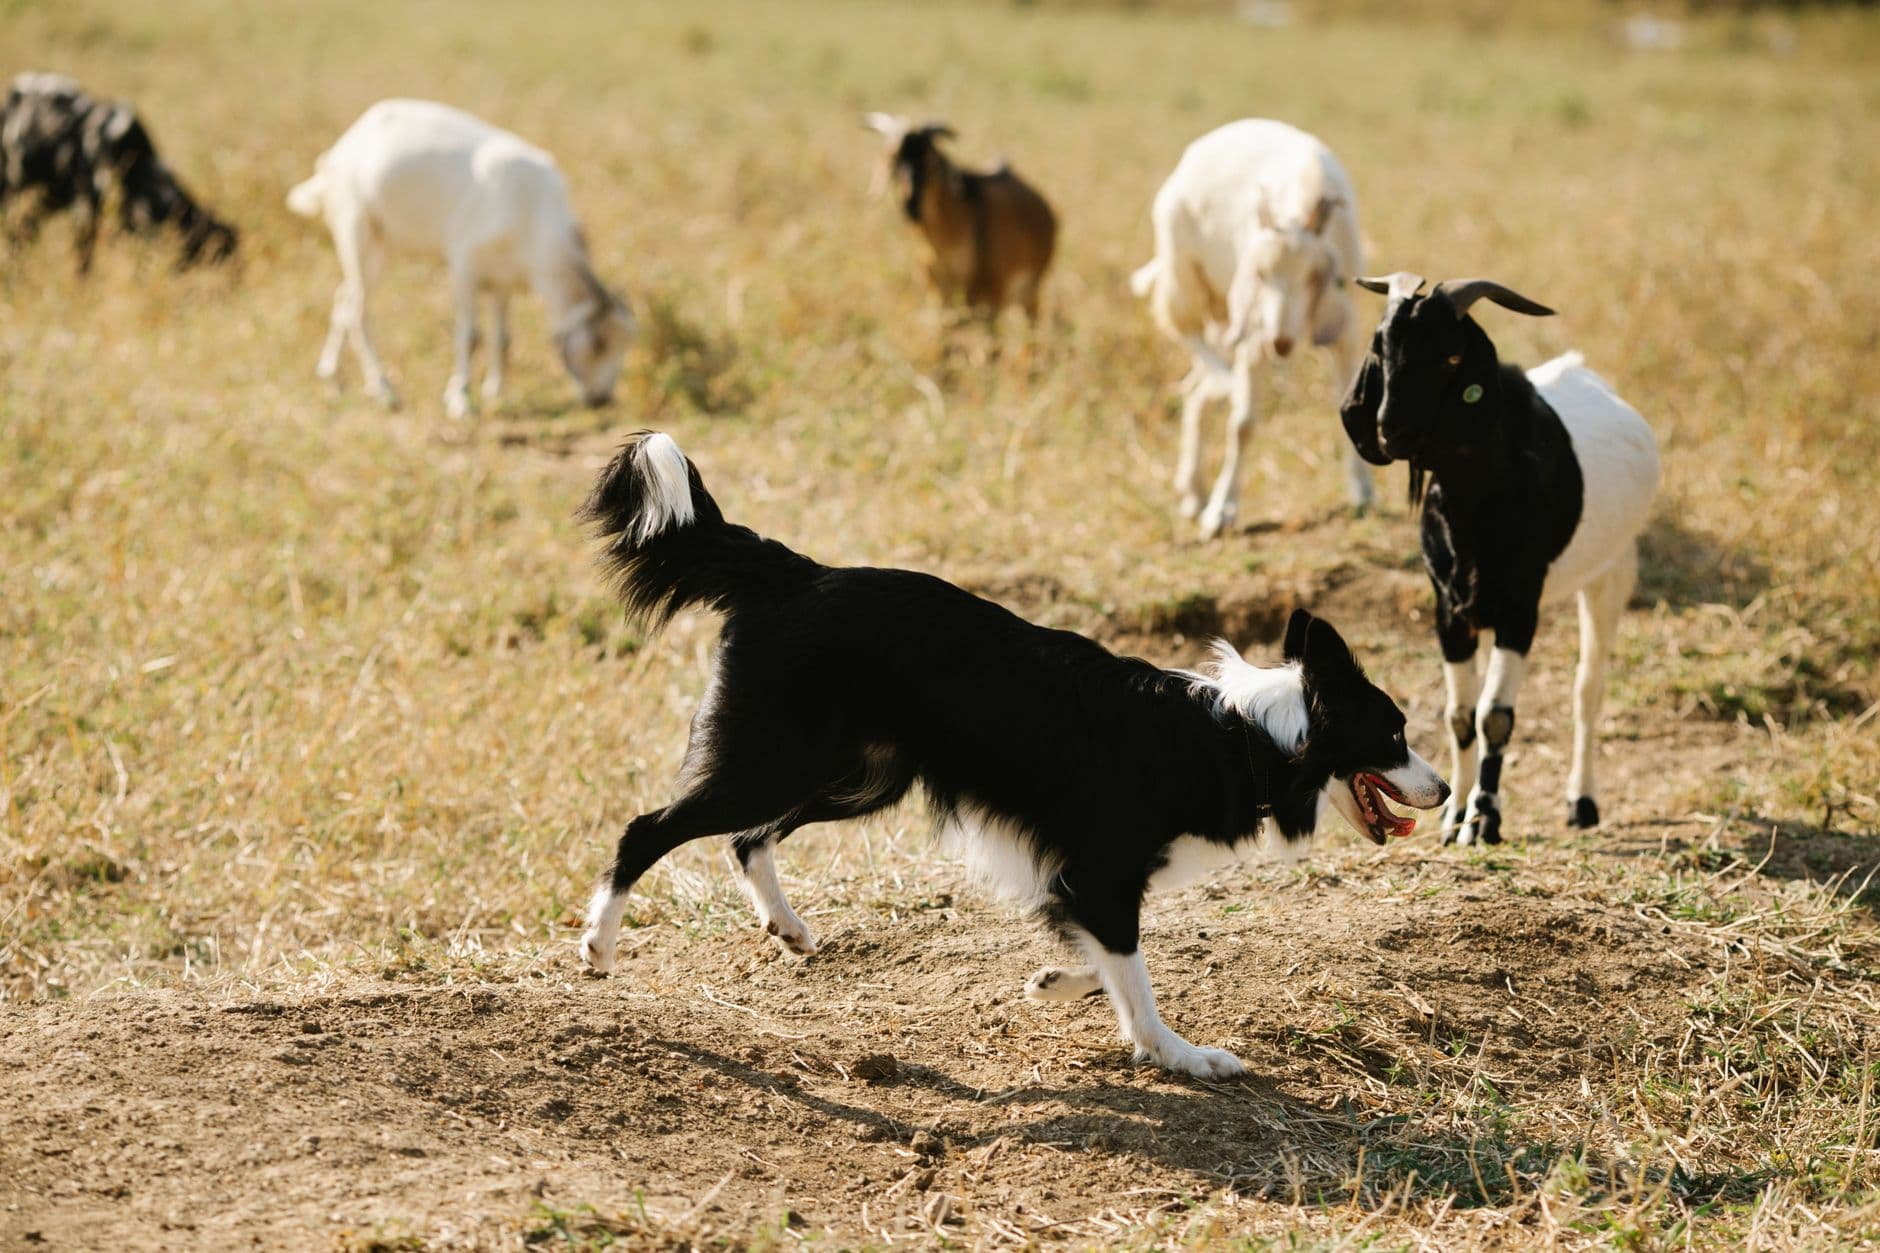
Agricultural operations get some of the clearest footing here, because working dogs on a farm often have an obvious, provable function. Livestock guardian dogs protecting sheep or cattle from predators, herding dogs actively used to move animals, and dogs used specifically for pest or predator control around grain storage all have a defensible business purpose under the same ordinary-and-necessary standard in Publication 535.
The expenses that typically qualify include:
| Expense type | Likely deductible if | Not deductible if |
|---|---|---|
| Food and vet care | Dog lives and works primarily on the farm | Dog is primarily a household pet |
| Training costs | Training is specific to herding, guarding, or predator control | General obedience training for a pet |
| Purchase price | Bought specifically for working purposes, with breed and use documented | Purchased as a family dog that happens to live on the property |
For a breeding operation raising working or sporting dogs as an actual business, with sales, a business bank account, and consistent recordkeeping, the dogs themselves become business assets. Feed, veterinary costs, stud fees, and even depreciation on breeding stock can be legitimate deductions, because the activity meets the definition of a trade or business rather than a hobby. That last distinction, hobby versus business, is one the IRS scrutinizes closely, and it's worth a conversation before you assume your side breeding income qualifies for full business treatment.
The dual-use trap that disqualifies most claims
Most dog deductions get denied for one reason: the dog lives a double life. It guards the shop during the day and sleeps on the couch at home every night. It's called a service animal but has no documented training tied to a specific task. It's a "farm dog" that mostly rides in the truck and visits the vet for routine care unrelated to any working function.
The IRS looks for consistency between how you describe the dog and how the dog actually lives. If you can't separate the personal use from the business or medical use, the deduction usually doesn't survive a closer look. This is exactly the kind of nuance that's easy to get wrong on your own and easy to get right with a second set of eyes before you file, not after.
Common Questions
Can I deduct my dog's food and vet bills if he just keeps mice out of my shop? General pest control by a dog that otherwise lives as a household pet usually doesn't meet the ordinary-and-necessary standard in Publication 535 (opens in new tab). If the dog has a documented, primary working role on your business property, with consistent evidence of that use, the costs have a much stronger case.
Does a therapy dog qualify for the same deduction as a service dog? Not automatically. Publication 502 (opens in new tab) is built around dogs trained to perform specific tasks tied to a diagnosed disability. Emotional support alone, without task-specific training documented by a physician, typically doesn't meet that standard.
I run cattle and use a livestock guardian dog. What records should I keep? Keep receipts for food, veterinary care, and training, along with notes or photos showing the dog's working role and where it's primarily kept. That documentation is what separates a working farm dog from a family pet if the IRS ever asks questions.
Can a breeding operation deduct dog-related expenses like a regular business? Yes, if the activity is run as an actual trade or business with a bank account, sales records, and consistent profit motive, rather than as a hobby. The hobby-versus-business distinction is one worth reviewing with your tax preparer before you claim significant deductions.
If you're not sure whether your farm dog, guard dog, or service animal situation actually qualifies, that's exactly the kind of question worth working through with someone who knows Brookings agriculture and small business tax rules from the inside. Reach out through /contact and we'll look at your specific situation before filing season turns into guesswork.